Impact investing is investing with the intention to create measurable social or environmental outcomes alongside a financial return. It's different from ESG investing. ESG ratings measure risk to a company. Impact measures what the company does to people and the planet.
Impact investing has two objectives. The first is a financial return. The second is a measurable outcome in the real world, such as lower emissions or wider access to healthcare. An impact investment needs both.
The Global Impact Investing Network (GIIN), a nonprofit network of impact investors, defines impact investments as investments made with the intention to generate positive, measurable social or environmental impact alongside a financial return. The GIIN says impact investments are compatible with returns from below market to above market rate. Investors who own public stocks generally target market-rate returns.
The term impact investing dates from 2007. That year, investors, entrepreneurs and philanthropists met at the Rockefeller Foundation's Bellagio Center in Italy to discuss ways to direct capital toward social and environmental goals. The participants came up with the label "impact investing."
Intentionality separates impact investing from conventional investing. An impact investor decides in advance which outcomes the money should support. A conventional investor might own the same stock without that intent. Without a return objective, impact investing becomes philanthropy. Without an impact objective, it's conventional investing with a different label.
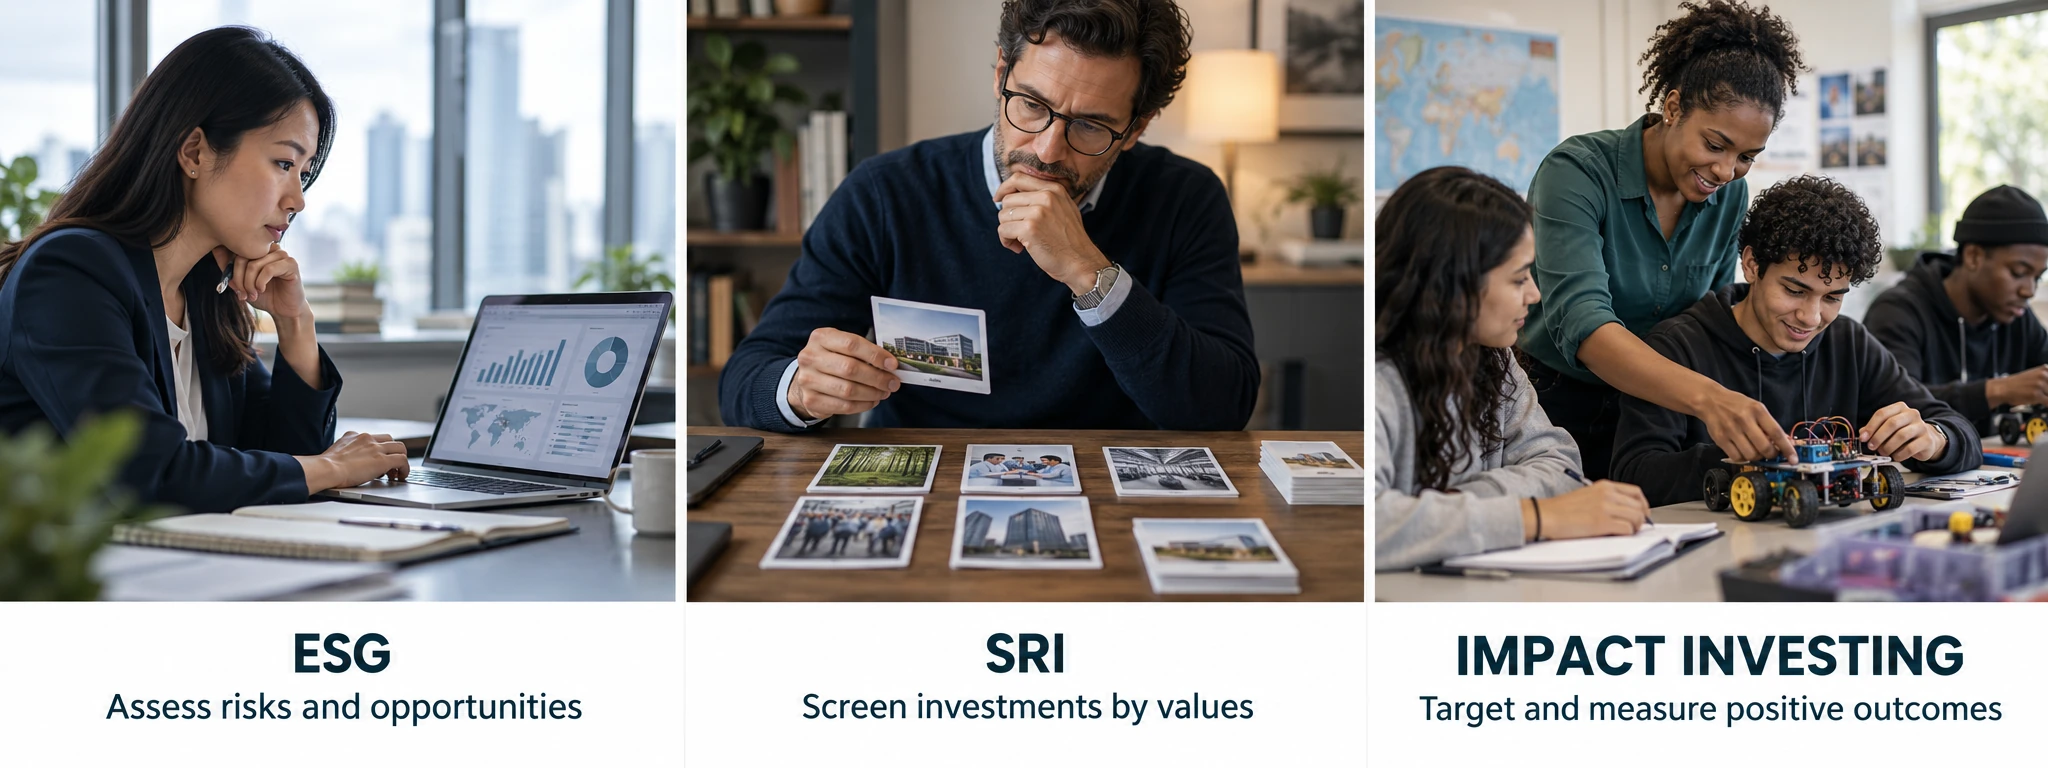
Impact investing, ESG investing and socially responsible investing (SRI) overlap, but each starts from a different question. ESG ratings measure financial risk to a company from environmental, social and governance issues. SRI is best known for negative screening, which excludes companies that conflict with an investor's values, such as tobacco makers. Impact investing measures the outcomes a company produces for people and the planet. In the US, the Forum for Sustainable and Responsible Investment (US SIF) treats impact investing as part of a wider field it calls sustainable and impact investing. Ziggma's ESG vs impact investing comparison covers the full difference.
Investors who own public stocks create impact in three ways: through engagement, by shifting capital between companies, and by buying new share and bond issues.
Engagement works through ownership. Owning a share carries a vote at the company’s annual meeting. Shareholders vote on directors, executive pay and proposals about climate targets and labor practices. Investors can also file proposals and raise issues with management directly.
Shifting capital works through prices. When investors move large amounts of capital out of some companies and into others, share prices move, and so does each company’s cost of capital. A falling share price makes new equity more expensive to raise, and a rising one makes it cheaper. The sums in play are large. Global sustainable funds held $3.73 trillion at the end of June 2026, according to Morningstar, and the Sierra Club’s strategy aims to “shift trillions of public and private dollars from the fossil fuel economy.” The evidence suggests these shifts move prices. Philippe van der Beck of Harvard estimates that each $1 moved into ESG stocks raised their market value by about $0.70. The effect tends to be larger for smaller companies, where the same amount of money is a bigger share of the stock.
New share and bond issues fund companies directly. A company receives investors’ money when it sells new securities, through an IPO, a follow-on share offering or a bond issue such as a green bond. Ziggma’s guide to public market impact investing covers all three in detail.
Impact is a spectrum, and most companies sit somewhere in the middle. The Impact Score rates every stock from 0 to 100 and sorts companies into five bands: Harmful (0–19), Negative (20–39), Mixed (40–59), Positive (60–79) and Profound (80–100).
A company creates positive impact when its core products or services address a real problem. Examples include solar panels, water treatment and affordable healthcare. The impact has to sit in the business model. A side project or a marketing campaign doesn't count.
A company also creates positive impact through how it runs its business, whatever it sells. Corporate stewardship covers how a company uses resources, pays its people and manages its supply chain. A manufacturer that cuts the energy and water it uses per unit produced shrinks its footprint every year. A company that pays fair wages improves the lives of its own workforce. A company that audits its suppliers for forced labor and unsafe conditions extends fair treatment to workers it doesn't employ directly.
Stewardship applies to every company. In sectors that can't change what they sell, it's the main route to positive impact. An oil and gas producer that finds and fixes methane leaks cuts real emissions at scale. Methane traps far more heat than carbon dioxide in its first two decades in the atmosphere, so fixing leaks pays off for the climate quickly.
Stewardship counts only when it shows up in measured results, such as lower emissions per unit or fewer safety incidents. A policy on paper isn't enough. The Impact Score measures stewardship through four sub-scores: Climate Action, Resource Use, Fair Labor and Accountability. These reflect factors such as carbon intensity, the gap between CEO pay and median worker pay, and supply chain labor standards.
A company with a small environmental footprint is held to the same stewardship standards as any other company. A software firm or a professional services firm doesn't run factories or sell harmful products. It still creates positive impact through how it treats people and how it governs itself. That means protecting customer data, paying staff fairly, reporting transparently and keeping strong governance. It can also do harm, through data misuse, unfair pay or weak oversight. A small footprint doesn't make a company neutral. It means stewardship carries more of the company's impact.
A company has negative impact when its products or operations cause harm, through pollution, unsafe working conditions or products that damage health. Impact investing doesn't require owning zero negative-impact companies. It requires knowing which ones you own and choosing deliberately.
Credible impact measurement tracks outcomes, such as tonnes of emissions avoided, rather than inputs like sustainability spending.
Inputs are the resources a company commits, such as a budget for energy efficiency. Outputs are the direct results, such as the number of factory lines upgraded. Outcomes are the changes in the real world, such as lower emissions per unit produced, lives saved or children educated. Impact investing judges companies on outcomes. Outcomes are the hardest of the three to measure, and that's why many sustainability reports stop at inputs.
Impact has no single unit the way returns have dollars. A water utility and a software firm affect different things, so comparing them takes scores by topic. Corporate impact disclosure is voluntary in many markets, and its quality varies from company to company. Gaps and loose definitions leave room for greenwashing. Ziggma's Greenwashing Files show what that looks like in practice.
Impact data comes from three kinds of source: company disclosures, public records and independent research. Company disclosures include sustainability reports and regulatory filings. Public records include government datasets such as the US EPA Greenhouse Gas Reporting Program and OSHA workplace injury records. Independent research covers academic studies, NGO investigations and investigative reporting. Disclosures alone aren't enough, because companies choose what they report.
Most investors don't gather this data themselves. They rely on impact data providers, specialist firms that collect these sources, check them against each other and turn them into scores that can be compared across companies. Impact data providers are different from ESG rating agencies. ESG rating agencies score financial risk to a company. Impact data providers score what the company does to people and the planet.
A credible impact data provider is independent of the companies it rates. It measures outcomes rather than policies. It also says when a number is an estimate rather than a reported figure. Estimates fill gaps where a company doesn't disclose a metric, and they're usually modelled from comparable companies. Investors should always be able to see which numbers are estimated. How impact data is built covers the method in more detail.
The most common public market impact themes are clean energy, water, healthcare access and financial inclusion. Stewardship adds a fifth route that applies to every sector.
Clean energy companies make or operate solar, wind, battery storage and grid equipment. The outcome is lower emissions from the power people use. Ziggma ranks the best renewable energy stocks by Ziggma Stock Score and Impact Score.
Water companies treat, test and deliver drinking water, and they handle wastewater. The outcome is safer water and less pollution in rivers and coasts. Ziggma covers the sector in its list of the best water stocks.
Healthcare companies create impact when they make care cheaper or easier to reach, through generic drugs, diagnostics or medical devices. The outcome is lives saved and more years lived in good health. Banks, lenders and payment companies create impact when they serve people the mainstream financial system leaves out. The outcome is access to credit, savings and insurance. High-cost lending that traps borrowers doesn't count.
A company doesn't need a green product to be an impact investment. A manufacturer that cuts its water use, a retailer that pays fairly across its supply chain and a software firm that protects user data all create impact through stewardship. Ziggma's list of green stocks includes companies from both routes.
Investors who'd rather own a fund can buy impact funds and ETFs that own baskets of these companies. Fund names and labels vary, so the holdings matter more than the name. Ziggma compares the best impact funds by what they actually own.
The biggest myth is that impact costs returns. The best long-run evidence points the other way.
The evidence doesn't support a built-in return penalty, and three independent studies point the same way. In a study by Schroders and Oxford's Saïd Business School, 8 of 10 random 40-stock portfolios of high-impact companies beat the MSCI ACWI IMI from 2010 to 2023. The Clean200, Corporate Knights and As You Sow's list of leading clean-revenue companies, returned 282.9% from July 2016 to January 2026, against 221.3% for the MSCI ACWI. In Morgan Stanley's Sustainable Reality data, $100 in the median sustainable fund grew to $171 from December 2018 to June 2026, against $159 in the median traditional fund. Past results don't guarantee future returns.
Investors weigh issues differently, but the measurement doesn't have to be subjective. Emissions, water use, injury rates and pay gaps are numbers that can be reported and checked. Values decide which outcomes an investor cares about most. Data decides how a company actually performs on them.
Private markets fund new companies directly, but public market investors have their own levers. Shareholders vote at annual meetings and can engage management. Listed companies also raise new money through share and bond issues, including green bonds. Public markets are also where most people's savings sit, through brokerage accounts, IRAs and 401(k) plans.
Impact investing and ESG investing measure different things. ESG ratings score financial risk to a company from environmental, social and governance issues. Impact data scores the outcomes a company produces for people and the planet. A company can have a strong ESG rating and a poor impact record, or the reverse. Ziggma looks at whether ESG funds outperform in a separate analysis.
Measuring a portfolio's impact means scoring each holding, then weighting those scores by position size. Start with an impact score for every stock and fund you own. Weight each score by its share of the portfolio, because a 20% position moves the total far more than a 1% position. Then check the portfolio's climate alignment, which expresses its emissions as a temperature. Finally, check for controversies a score might miss, such as lawsuits, spills or labor disputes.
Ziggma Impact X-Ray applies this method to a linked or uploaded portfolio. It shows the Impact Score for every holding, the portfolio's spread across the five Impact Score bands, its Global Warming Potential and its Controversy Score. The Controversy Score rates each holding from 0 to 100 on its exposure to controversies such as lawsuits, spills and labor disputes. A higher score means more serious controversy exposure. The Impact Score data comes from ACA Ethos, an independent specialist in impact data. ETFs get a fund-level Impact Score rather than a holding-by-holding look-through. The Impact X-Ray page shows how it works.
Global Warming Potential is Ziggma's temperature alignment metric for a portfolio, expressed in degrees Celsius. It's unrelated to the IPCC emissions conversion factor of the same name. The S&P 500 has a Global Warming Potential of 4.0°C, based on September 2026 emissions data. The Paris Agreement aims to hold warming well below 2°C. Ziggma explains the metric in its guide to portfolio temperature alignment.
The impact investing guide sets out six strategies for changing what a portfolio funds.
Interest in impact investing keeps rising, but money hasn't followed. Morgan Stanley's 2026 Sustainable Signals survey of 2,250 individual investors found that 92% are interested in sustainable investing, up from 88% in 2025. The average allocation to sustainable investments fell to 31%, from 33% a year earlier. Performance is the top reason investors give for their interest. 64% plan to increase their sustainable allocations over the next year.
Mandatory sustainability reporting is shrinking in both the US and the EU. The SEC adopted climate disclosure rules in March 2024, but companies never had to comply. The rules were stayed during litigation in the US Court of Appeals for the Eighth Circuit. In May 2026, the SEC proposed rescinding them entirely. The public comment period closed on August 3, 2026, and a final vote is expected in late 2026 or early 2027.
The EU narrowed its Corporate Sustainability Reporting Directive (CSRD) through the Omnibus I package, which took effect on March 18, 2026. CSRD reporting now applies only to EU companies with more than 1,000 employees and more than €450 million in net turnover.
Fewer companies will publish mandated sustainability data as a result. That makes independent impact data more important, because investors can't rely on company disclosures alone.