Palo Alto Networks (PANW) beat forecasts and raised its full-year outlook above Wall Street's. The business got stronger. At 23.6x sales, the stock already prices a lot of that in.
Since added (12 Jan)
+80.0%
S&P 500: +5.0%
Analyst consensus
$410
+21% upside, Wall Street's view
Ziggma Stock Score
76
9from 85
Impact Score
73
11from 84, Positive band
Best, base, downside case
Estimates, not promises. The price can end up outside this range, including below the downside case, and you can lose money. This is research, not personal financial advice.
Data as of 18 Nov 2026 close; scores as of 19 Nov 2026
Palo Alto reported first-quarter results after the close on 18 Nov. Revenue for the three months to 31 Oct was $3.44B, up 39% from $2.47B a year ago and ahead of the $3.31B analysts expected. Adjusted earnings per share, which leave out share-based pay and acquisition costs, came in at $1.05, against $0.93 a year ago and a $0.97 forecast. Growth includes the CyberArk acquisition, and the company doesn't split out its share.
Quarter to 31 Oct: this year against last
Includes CyberArk. The company doesn't split acquired from organic growth. Adjusted figures leave out share-based pay and acquisition costs.
Palo Alto now expects $14.52–14.57B of revenue for the year to July 2027, up from $14.1–14.2B in August and above the $14.17B analysts expected (LSEG). The chief financial officer called it "materially raising our full year guidance" in the earnings release. Shares rose about 7% after hours.
New full-year outlook, year to July 2027
Revenue
$14.52–14.57B
Was $14.1–14.2B in AugustAnalysts expected $14.17B
Next-Generation Security ARR
$11.475–11.525B
Was $11.075–11.175B in August
Adjusted earnings per share
$4.26–4.30
Analysts expected $4.18
Next quarter: revenue of $3.53–3.55B (36–37% growth) and adjusted earnings per share of $1.01–1.03.
Next-Generation Security ARR, the yearly subscription revenue from Palo Alto's newer platforms, rose 66% to $9.73B. Contracts signed but not yet booked as revenue grew 35% to $21.0B. Under official GAAP accounting, operating income fell to $96M from $309M, mostly because of acquisition costs, including $95M for CyberArk.
Next-Generation Security ARR
$9.73B
Up 66% from a year ago
Signed, not yet booked
$21.0B
Remaining performance obligation, up 35%
The stock is the problem. It's up 80% since our first report in January, while the S&P 500 gained 5%. You pay $23.60 for every $1 of yearly sales, against a five-year average of $13.90, and 81.3x this year's expected profit. Its 944.8% profit growth forecast looks big only because GAAP earnings per share shrank 75% in fiscal 2026. We saw the same pattern at Visa, where the price ran ahead of the business. After an 80% run, it may also fill more of your portfolio than you planned.

The Ziggma Stock Score tells the same story. It fell to 76 from 85 in January, even though results got better. The likely reason is the price. Growth, Profitability and Financial Health all score 67 or higher. Valuation scores 6 out of 100.
Since our first report: 12 Jan 2026
Palo Alto plans to buy Applied Compute, a platform for tuning and running open-weight AI models, for $4.5B paid in Palo Alto shares, pending antitrust review. Paying in shares shrinks each existing share's slice of the company. The board extended its $1B buyback authorization to 31 Dec 2027, which can offset some of that. The average analyst target of $410 implies 21% upside. That's Wall Street's view, not ours.
All three start from Palo Alto's own outlook: $14.545B of sales for the year to July 2027, the middle of its range, spread over about 831M shares once Applied Compute is paid for in stock. They differ only in what investors pay for each $1 of sales.
Downside case
$243 −28%
Investors pay the five-year average of 13.9x sales. That's still 57x this year's expected adjusted profit.
Base case
$328 −3%
Investors pay 18.75x sales, halfway between today's multiple and the average.
Best case
$413 +21%
Investors keep paying 23.6x sales for growth like this quarter's.
Palo Alto doesn't pay a dividend. Wall Street's view, not ours: the average analyst target is $410 (+21%), close to our best case.
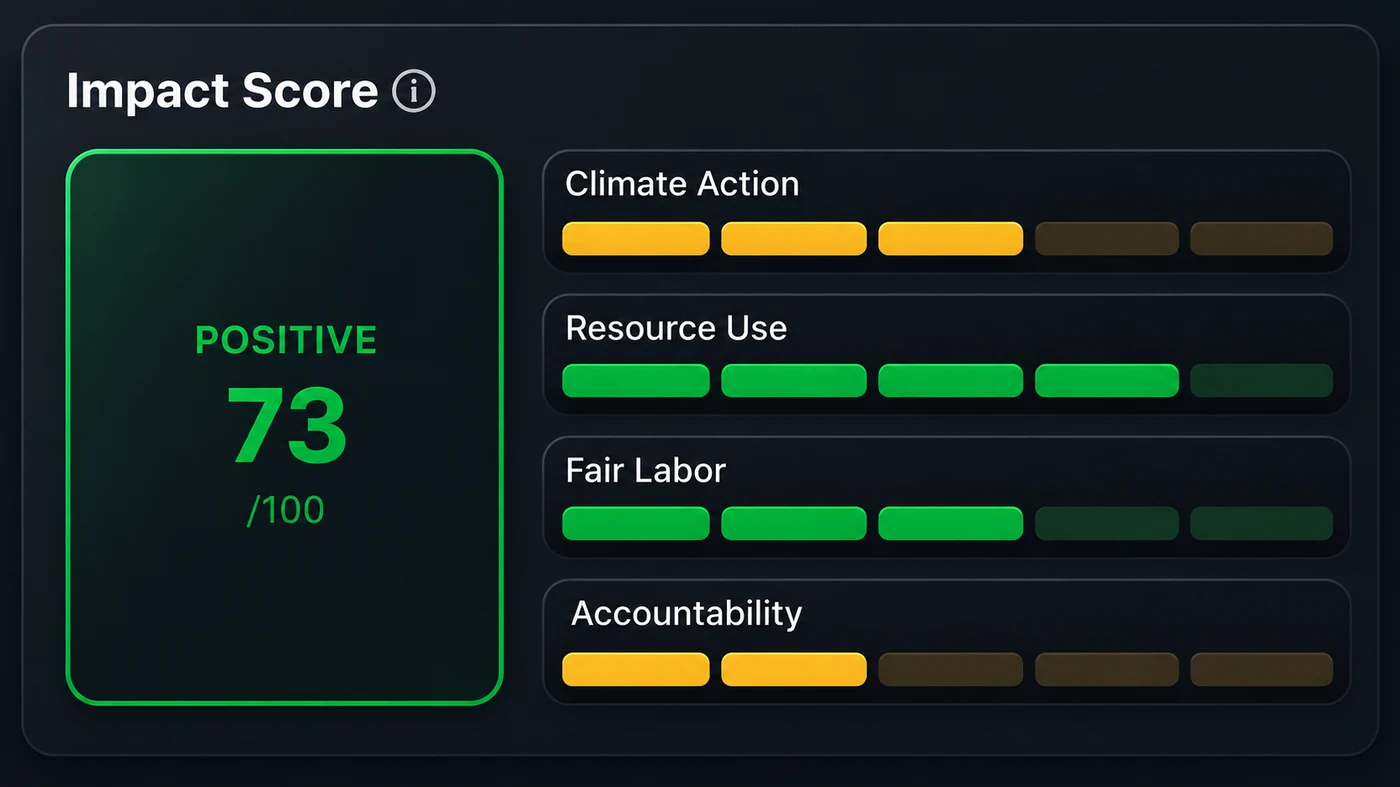
Palo Alto's software guards the networks that hospitals and power grids run on, and the personal data inside them. The Impact Score fell to 73 from 84, still in the Positive band, and the weak spots are Accountability (44) and a CEO paid 269x the median worker. CEO pay is something shareholders can vote on.
Too expensive at this level. The business got stronger, but the stock now costs 23.6x sales against a 13.9x five-year average.
Data as of 18 Nov 2026 close. Scores and valuation from Ziggma, 19 Nov 2026.
See the Ziggma Stock Score and Impact Score for every stock you own, and how your portfolio's warming potential compares with the S&P 500.
Create a free accountOr find more stocks like Palo Alto in the impact stock screenerNew to screening by impact? Our positive screening guide shows how to find companies by what they do well.

