Most clean power clocks out at sunset. Ormat Technologies (NYSE: ORA) pulls heat from underground, so its plants never stop. Wall Street, for now, doesn't want the stock: at $88.10, shares sit 40% below their June high of $146.39.
Every GoodStocks pick has to pass two tests: strong return prospects and real benefits for the world. Ormat aces the second one by default, since it sells carbon-free electricity and the gear to make it. Companies that pass both have tended to beat the market, according to four independent studies.
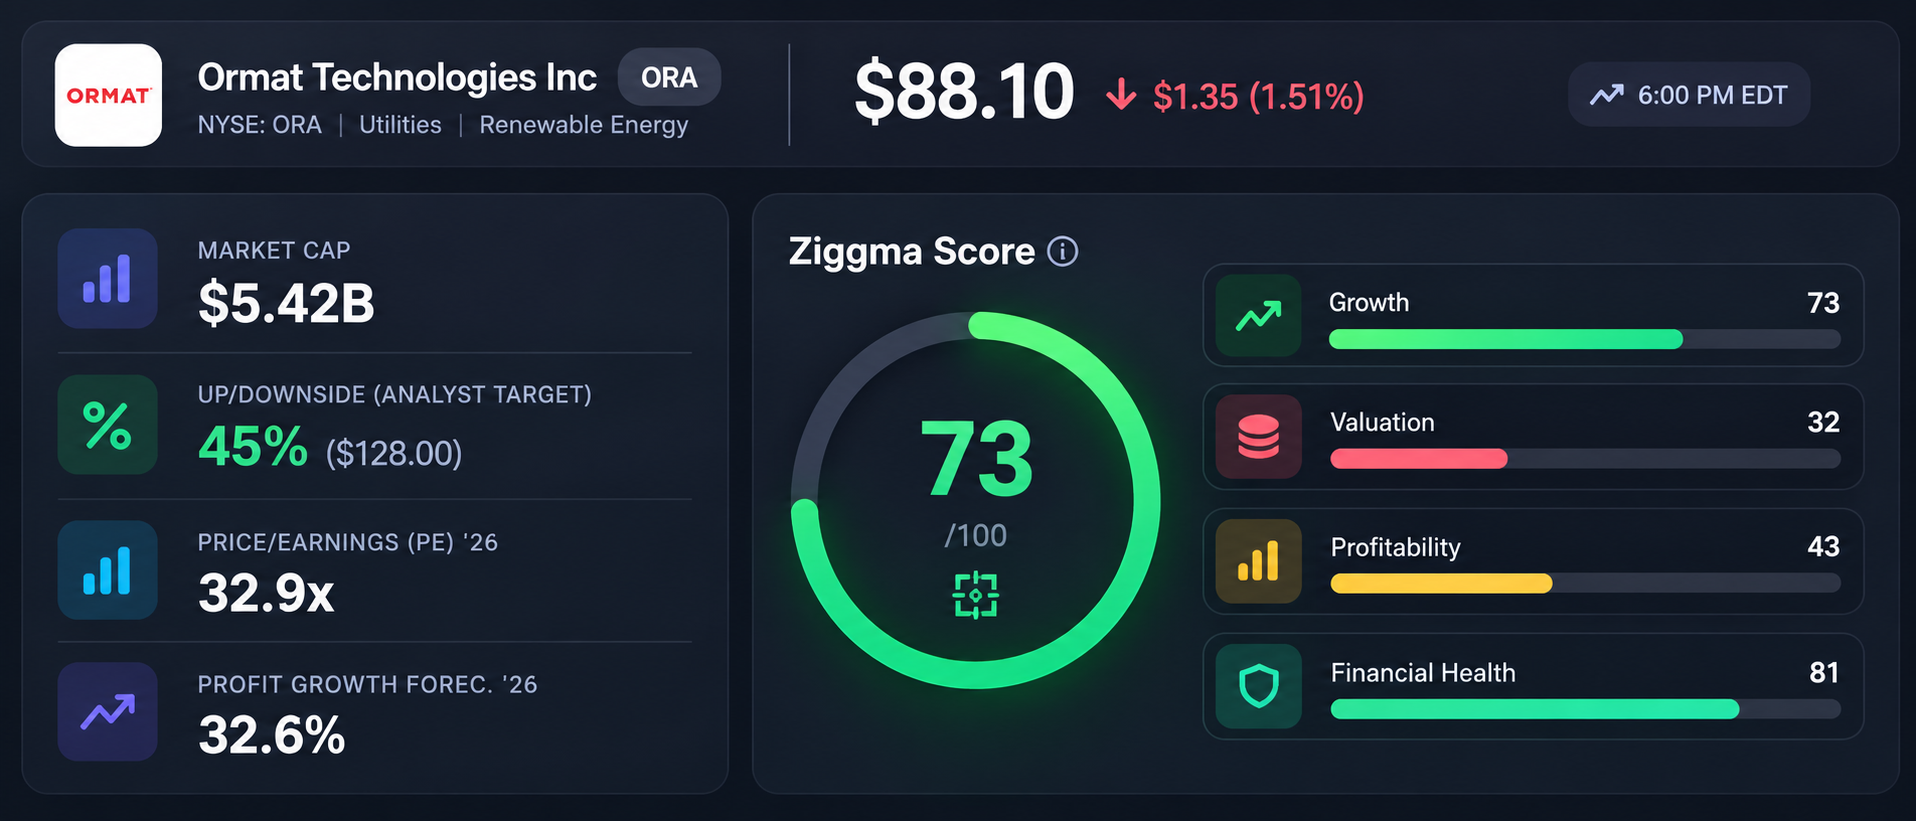
We think the sell-off went too far. Revenue jumped 43% in the first half of 2026 and management raised its forecast. Analysts' average target of $128 implies 45% upside. We see $105–115 within a year, and the November 3 midterms could add a tailwind.
Source: Ziggma
Management expects 2026 revenue of $1.15–1.20 billion, up about 19%, and profit is forecast to grow 33% this year. At 4.7x sales, close to its cheapest level in five years, patient investors get that growth at a discount.
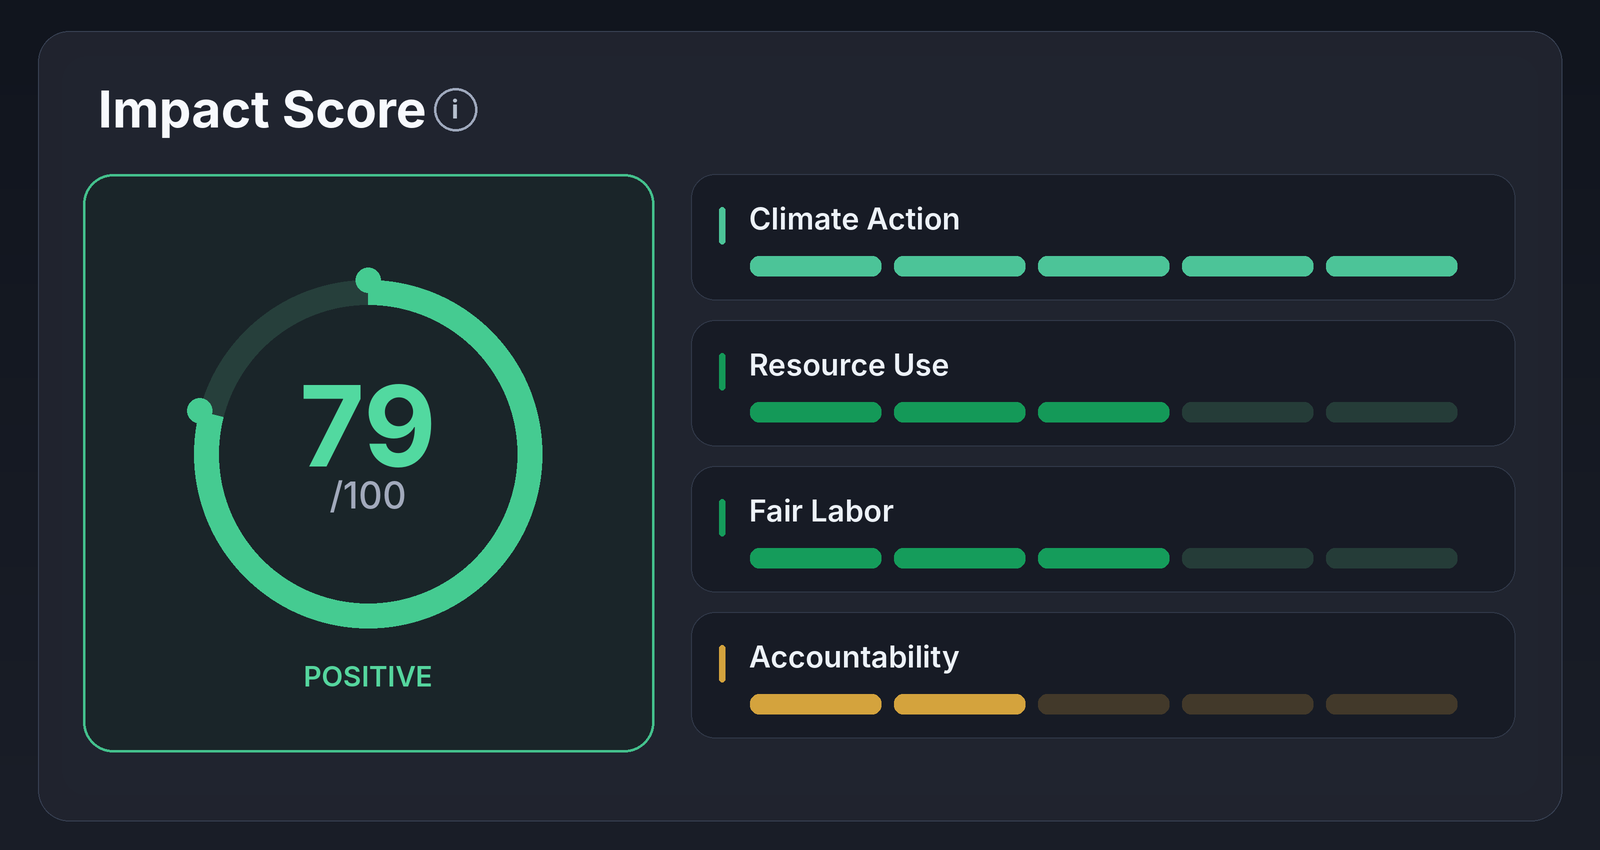
Ormat's plants avoided about 2.5 million tons of carbon dioxide emissions in 2024, over 11x what the company emitted, according to its sustainability report. Climate Action is Ormat's strongest impact rating on Ziggma (see our best climate stocks).
Source: Ziggma
Ormat, based in Reno, Nevada, has built geothermal plants for 60 years. Its portfolio reached about 1,850 megawatts in October 2026, in the US, Kenya, Guatemala, Indonesia and Dominica. Ormat also sells power equipment to other developers and runs large battery sites, like the 80-megawatt Shirk facility in California.
The moat is real. Good geothermal sites are scarce, and Ormat holds the land, water rights and decades of drilling data. In February, Ormat signed a contract with utility NV Energy to supply up to 150 megawatts of new geothermal power for Google's data centers, from plants due in 2028–2030, pending state approval.
Revenue grew 12.5% in 2025 to $989.6 million, though profit stayed flat at $123.9 million because US grid limits cut output. First-half 2026 revenue rose 43% to $662.7 million, helped by a large equipment sale. In the June quarter, storage revenue nearly tripled to $42.8 million at a 56% gross margin on high East Coast power prices.
At its September 8 investor day, Ormat trimmed its 2028 profit target by 3%. UBS then downgraded the stock on October 1, cutting its target from $157 to $100 on slower storage growth. A 3% trim two years out doesn't justify a 40% drop, and the plan still calls for roughly doubling capacity to 3.5–3.7 gigawatts by 2030.

Source: Ziggma
At 4.7x sales, Ormat trades near the bottom of its 4.3–7.9x range since 2022. At 32.9x this year's earnings it looks pricier, hence a Valuation sub-score of 32. Growth scores 73 and Financial Health 81. Profitability, at 43, is the soft spot.
Geothermal and battery storage kept their full federal tax credits for projects starting construction through 2033 under the 2025 tax law President Trump signed, and Energy Secretary Chris Wright backed the geothermal credit. In September, the Energy Department selected Ormat for up to $35 million in project funding.
Democrats need just three more seats to win the House. A Democratic House couldn't override a veto before 2029, but it could block fresh cuts to clean energy credits, and House Democrats' Energy Bills Relief Act would speed geothermal permits on public lands. Our position: a Democratic win is a modest positive that lowers the risk of a policy shock. The stock doesn't need it.
Storage profits ride on volatile power prices and could shrink faster than expected. Higher interest rates make Ormat's heavy borrowing costlier. Next-generation geothermal, which cracks open hot dry rock, is unproven at scale, with Ormat's first 25-megawatt project due in late 2029. Much of Ormat's manufacturing and leadership is in Israel, where regional conflict can disrupt work.
We value Ormat on sales, because depreciation on new plants holds down its reported profit. At 5.5–6x this year's guided sales of about $1.175 billion, still below the middle of its range since 2022, shares would be worth $105–115, or 20–30% above today.
Cash flow supports that. Operations brought in $335 million in 2025, about 2.6x net income, so the stock trades at roughly 16x operating cash flow. The catch is spending. Ormat spent $620 million on plants last year and has outspent its operating cash every year since 2021, borrowing the difference. That's why we stay at the low end of the range. The $128 analyst average looks stale after recent cuts.
Grids lean on gas and coal at night and on still days. Geothermal fills that gap without burning anything, and Ormat's batteries move daytime solar power into the evening. Ormat also met its goal of cutting emissions per megawatt-hour by an average 5% a year against 2019. That's why Climate Action is Ormat's top impact rating.
Ormat has run plants at Kenya's Olkaria field for over two decades and co-funded Honduras' first bilingual public school. Women held 44% of its board seats in 2024. Fair Labor and Resource Use rate solidly but trail Climate Action.
Accountability is Ormat's weakest impact rating, and we can't pin that on a single event. In March 2021, short seller Hindenburg Research accused Ormat of corruption in Kenya, Guatemala and Honduras. Ormat called the claims inaccurate but moved compliance duties away from two executives questioned over a previous employer.
Ormat sells what data centers and grids are short of: clean power that never stops. The stock fell 40% on a small guidance trim, while its tax credits are locked in through 2033. A Democratic win in November would make that policy floor sturdier. At 4.7x sales, patient investors are paid well to wait. Compare Ormat with other top scorers in our free stock screener or our list of the best renewable energy stocks.
______________________________________________________________________________
Disclaimer
This information is provided solely for general information and educational use. It is not intended as, and should not be construed to be, financial, investment, tax, legal, or other professional advice. Data used in the analysis is derived from third-party sources and applicable at the time of publication of the analysis. No representation or warranty is made as to the accuracy or completeness of the information or any analysis herein.
Ziggma is not registered or licensed as a financial advisor, broker-dealer, or tax professional. Readers should perform their own independent research and seek advice from appropriately qualified professionals before making any financial, investment, or legal decisions.
You should presume that, as of the date this report is published or any related communication referencing publicly traded securities or assets, Ziggma team members may hold positions in the securities or assets discussed and could benefit financially from price movements. Positions may be changed without notice.
There is no duty to revise or update the content after publication. Neither Ziggma nor any affiliated parties accept responsibility for market changes, economic developments, or subsequent events that could affect the relevance or accuracy of the information.
Forward-Looking Statements
This report may include forward-looking statements, such as forecasts, projections, estimates, or expectations regarding financial outcomes, market dynamics, or future corporate developments. These statements are based on assumptions that may not hold true, and actual results may vary materially. The author undertakes no obligation to update or revise any forward-looking statements as circumstances change.
Third-Party Data & External Sources
Certain information is sourced from third parties. Nonetheless, the accuracy, completeness, and timeliness of such information cannot be assured. Ziggma disclaims any responsibility for errors or omissions in third-party data and does not endorse, verify, or assume accountability for the methodologies or conclusions of external sources.
AI-Generated Enhancements
AI tools can be used to enhance clarity, structure, and brevity, and to assist with research organization, ideation, and analytical review.
Redistribution
You may share this report for informational purposes. However, reproduction, distribution, republication, or modification of any portion of the content, in whole or in part, without prior written consent is prohibited.
Investment Risk Disclosure
All investing carries risk of loss. Historical performance does not guarantee future outcomes. References to specific securities, companies, or strategies are for informational purposes only and do not constitute recommendations or endorsements. Any use of, or reliance on, the information in this report is entirely at the reader’s own risk.
Neither Ziggma nor affiliated parties shall be liable for any direct or indirect losses or damages of any kind arising from the use of this report or reliance on its contents. By accessing this report, you agree to indemnify and hold harmless Ziggma and affiliated parties from any claims, liabilities, or damages resulting from your use of the material.
You alone bear responsibility for your decisions. Use this information at your own discretion and risk.