TJX Companies (TJX) grew sales 6% last quarter, and shoppers kept coming back to T.J. Maxx, Marshalls and HomeGoods. Two of the three reasons for owning it in our first report in April 2026 held up: every division grew sales at existing stores, and TJX is returning about $3.0B through buybacks this year. At 26x forward earnings, the stock is valued below the 5-year average of 27x.
Every season, brands make more clothes and home goods than they can sell. TJX's buyers pick up that surplus and put it on shelves where it gets bought and worn instead of destroyed. That waste prevention, plus a climate record better than most large companies', earns TJX an Impact Score of 67, in the Positive band. We've tracked the score since our first report. The gaps we're watching are excessive CEO pay and its record on fines.
−11.3%
S&P 500: +0.5%
$170
+22% upside, Wall Street's view, not ours
91
3from 94
67
4from 71, Positive band
Best, base, downside case
Each case multiplies estimated profit per share for the year to January 2028 by a price to earnings multiple: $6.05 at 30.7x projected earnings for the best case, $5.77 at 27.2x for the base case and $5.56 at 20.9x for the downside case. See what each case assumes
Estimates, not promises. The price can end up outside this range, including below the downside case, and you can lose money. This is research, not personal financial advice.
Data as of 19 Nov 2026 close; scores as of 20 Nov 2026
TJX reported results before the market opened on 18 Nov. For the three months to 31 Oct:
Sales beat forecasts. Costs kept profit from keeping up.
Quarter to 31 Oct, this year against last
Analysts expected $15.80B
Analysts expected $1.33
Freight and fuel costs rose
Marmaxx, the T.J. Maxx and Marshalls division and about 58% of sales, grew comparable sales 2%. HomeGoods grew 5%, Canada 6% and the international business 8%, according to the earnings release. The shares jumped 8% that day.
What TJX expects next: adjusted earnings per share
Quarter to 31 Jan 2027, includes higher fuel costs
Year to 31 Jan 2027
Year to 31 Jan 2027
Our first report on 28 Apr 2026 made three arguments. Here's how each held up:
The business is doing what we expected. Profit growth is the part that's lagging.
Our September update called Marmaxx's weak summer a buying mistake TJX could fix by the fourth quarter. Marmaxx improved to 2% from 1%, and management expects more in the fourth quarter, so that call still needs the holiday numbers.
The stock is down 11% since April, while the S&P 500 is roughly flat. It's up 7% since September, when we put its value near $155. It sits 17% below its June closing high of $168.41.

The Ziggma Stock Score is 91, down from 94 in April. Each pillar ranks TJX against its peers:
The takeaway: the score slipped 3 points while the price fell 11%, so the business held up better than the stock.
Since our first report: 28 Apr 2026
The average analyst target of $170 implies 22% upside. That's Wall Street's view, not ours.
All three value TJX on its profit for the year to January 2028. Analysts expect $5.56–6.05 a share, $5.77 on average. Those estimates leave out one-time items, but next year they should match official (GAAP) profit, because TJX expects no more tariff refunds. The cases differ in where earnings land and in the multiple of projected earnings investors pay.
Downside case
$116 −17%
Earnings land at the low end of estimates, $5.56 a share, and the stock trades at 20.9x projected earnings, a 20% markdown from today's 26.1x.
Base case
$157 +13%
Earnings land in the middle, $5.77 a share, and the stock trades at 27.2x projected earnings, its five-year average.
Best case
$186 +33%
Earnings reach the top of the range, $6.05 a share, and the stock trades at 30.7x projected earnings, its multiple when we first covered TJX.
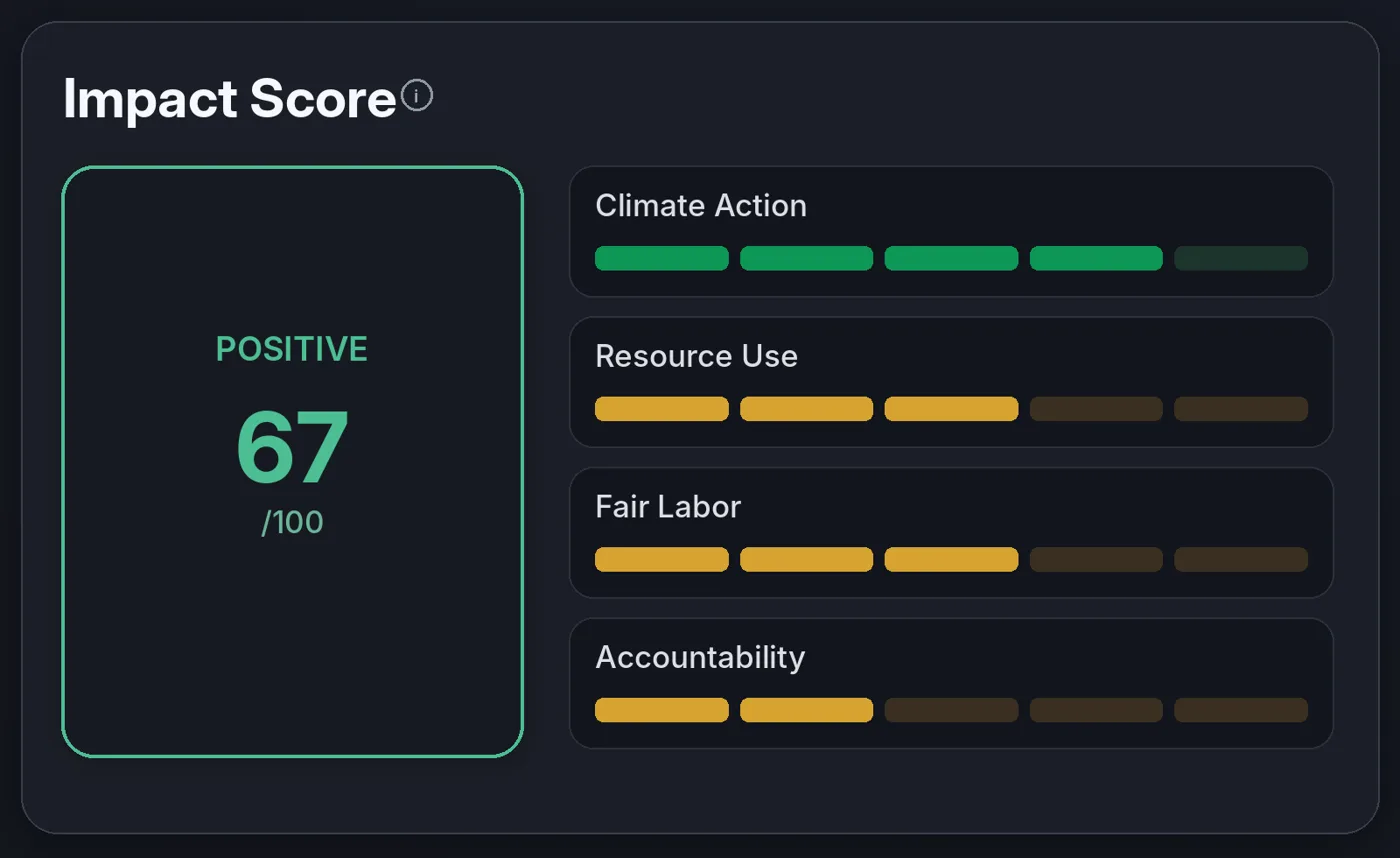
TJX gives unsold clothes and home goods a second chance at a buyer. The Impact Score is 67, in the Positive band. This quarter TJX published its 2026 corporate responsibility report, with its first climate disclosure mapped to the international standard investors use for climate risk. Strengths first, then weak spots:
The model and the climate record carry the score. Pay and fines hold it back.
Thesis intact, with margins on watch. Shoppers and sales held up, and the stock costs less than its five-year average. But the adjusted pretax margin slipped 0.2 points to 12.5%, and the full-year profit outlook sits just under forecasts. Our base case is +13%, plus the dividend, if investors pay the usual multiple on next year's profit.
Data as of 19 Nov 2026 close. Scores and valuation from Ziggma, 20 Nov 2026.
See the Ziggma Stock Score and Impact Score for every stock you own, and how your portfolio's warming potential compares with the S&P 500.
Create a free accountOr find more stocks like TJX in the impact stock screenerNew to screening by impact? Our positive screening guide shows how to find companies by what they do well.

