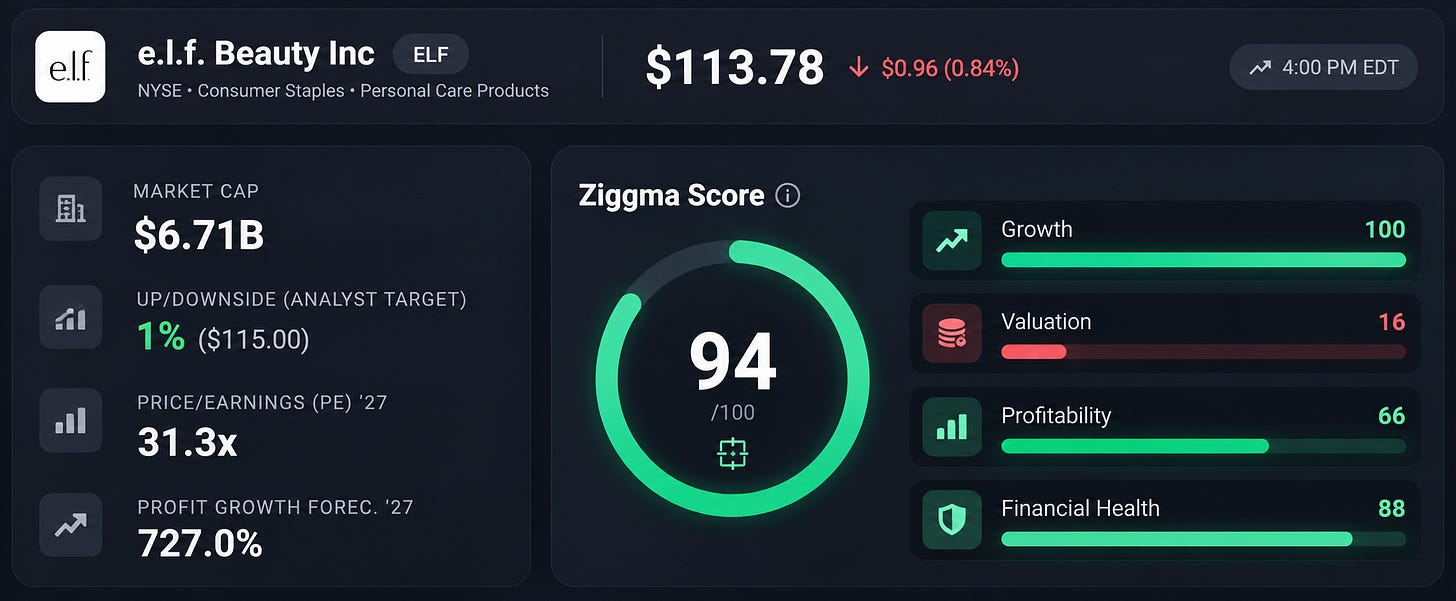
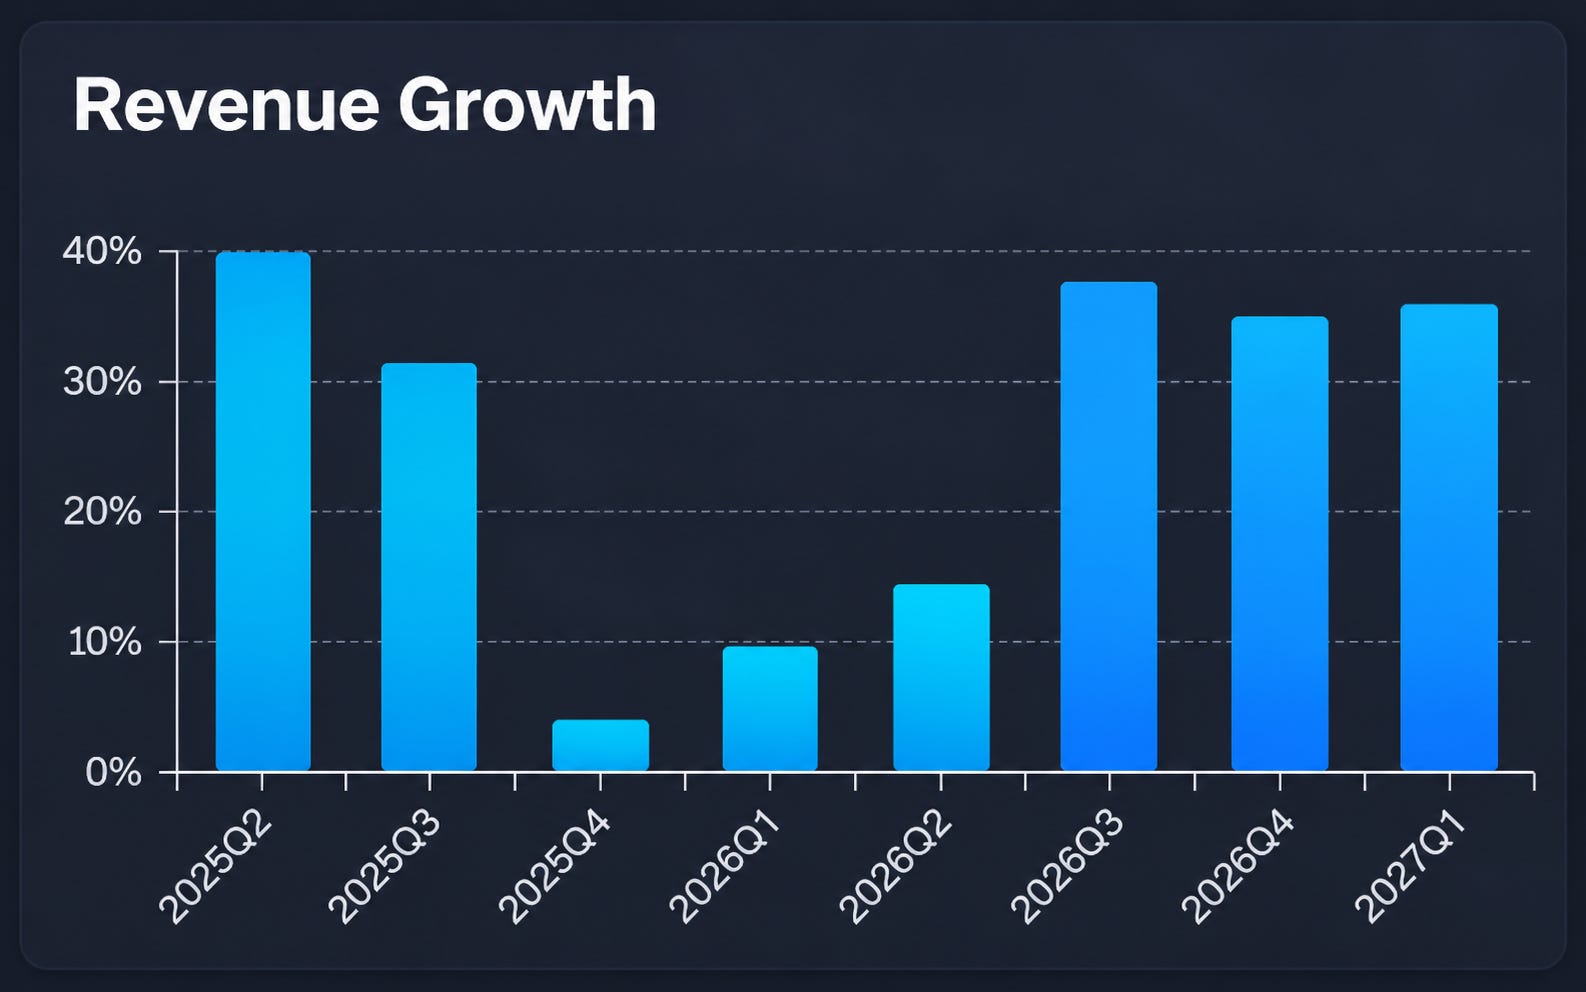
e.l.f. Beauty (NYSE: ELF) has grown sales for 30 quarters in a row, and the streak is speeding up. Sales growth was 14% in the quarter to September 2025, then 35% in the March quarter and 36% in the June quarter, when revenue hit $479 million. Management expects another mid-30s jump this quarter and raised its full-year forecast.
ELF easily makes it into the GoodStocks universe. Every stock in our GoodStocks series has to clear the same test: shareholder returns and real-world impact that pull in the same direction, a pairing that four independent studies link to market outperformance. e.l.f. passes it honestly. A $10 primer won’t cool the planet, but how a company treats the people who make its products, what it pays its CEO and who sits on its board are choices, and e.l.f. keeps making good ones.
The shares have nearly doubled since their late-spring low to $113.78. Analysts see almost no upside. We disagree. If earnings grow 15–20% a year and the stock holds at 30x, shares would be worth $160–183 by early 2029, 40–60% above today.
Source: Ziggma
Sales rose 25% in fiscal 2026 (the year to March) to $1.64 billion, and cash from operations climbed 59% to $213 million even as reported profit sank. Management expects adjusted earnings of $3.50–3.55 per share this year, about 31x at today’s price for a company that has gained market share seven years running.
In fiscal 2025, 73% of e.l.f.’s products were made in Fair Trade Certified factories, where workers earn a premium on every certified order. Employees rate the company highly, and its board is majority women.
Source: Ziggma
e.l.f. started in Oakland in 2004 selling $1 makeup online, and 75% of e.l.f. Cosmetics products still cost $10 or less. The company now runs e.l.f. Cosmetics, e.l.f. SKIN, Naturium, Well People and rhode, Hailey Bieber’s skincare line, plus a new e.l.f. Hair range sold at Target.
Rhode changed the shape of the business. e.l.f. bought it in August 2025 for $800 million upfront, plus up to $200 million more if rhode hits growth targets. It’s hitting them: rhode’s sales rose 80% to $390 million last fiscal year, and it launched with Sephora in 19 European countries in September.
How defensible is this? Makeup has almost no switching costs. e.l.f.’s edge is cost discipline and a knack for reaching young shoppers through TikTok Shop and a makeup game on Roblox. e.l.f. Cosmetics ranks No. 1 in US mass cosmetics by units sold, according to the company, a lead it has to win again every season.
Revenue has grown 33% a year over the past five years, and the past three quarters show growth picking up again. Sales rose 14% in the quarter to September 2025, 35% in the March quarter and 36% in the June quarter. Management expects growth in the mid-30s again this quarter and 18–20% for the full fiscal year, up from 12–14% in May.
Source: Ziggma
Rhode is the biggest engine. Sales rose 80% to $390 million last fiscal year, and the brand added about $160 million in the June quarter alone. It’s sold in fewer than 20% of Sephora stores worldwide, and it launched in 19 European countries in September, so the shelf space is still filling in. International sales grew 61% in the June quarter, and e.l.f. enters Brazil with Sephora this fall. New categories add more runway: e.l.f. Hair launched at Target in June, and e.l.f. SKIN heads to Dollar General.
The core e.l.f. brand is the soft spot. Its sales slipped in the June quarter against a tough comparison, and management expects growth excluding rhode of 6–7% this year.
Cash is the clearest read on this business. Operations generated $213 million in fiscal 2026, up 59% and roughly 8x reported net income. Cash on hand reached $344 million by June, even after e.l.f. bought back $50 million of its own stock. That cash comfortably covers interest on the $842 million of debt taken on for rhode, and Ziggma’s Financial Health sub-score of 88 reflects it.
Reported net income fell 77% to $26 million in fiscal 2026, almost entirely because of rhode. The deal added interest and accounting charges, including a $57.6 million charge triggered because rhode beat its growth targets. Excluding deal costs, profit fell just 6%, and that low base explains the 727% profit growth forecast on Ziggma.
At 31.3x next year’s earnings, e.l.f. trades far below its five-year average of 79x reported earnings, but above the beauty industry’s roughly 26x (Zacks, late 2025). Ziggma’s Valuation sub-score of 16 reflects that premium, while Growth scores a perfect 100 and Profitability 66.
The core e.l.f. brand is leaning on price increases while unit volumes shrink. Rhode carries much of the growth, tying the story to one young brand and its famous founder. Many products are made in China, so tariff policy can swing margins. The stock lost more than half its value between late 2025 and spring 2026.
The average analyst target is $115, just 1% above today’s price. We think analysts are pricing a messy year rather than the business underneath it. Earnings growth of 15% a year at a steady 30x points to about $160 by early 2029. If rhode’s rollout abroad keeps working and margins recover as tariffs ease, 20% growth gets the stock to about $183, roughly 60% upside.
Skincare doesn’t pull carbon out of the air, so e.l.f.’s Impact Score of 70 comes from how it runs the business. That’s the same stewardship lens we applied to Genpact.
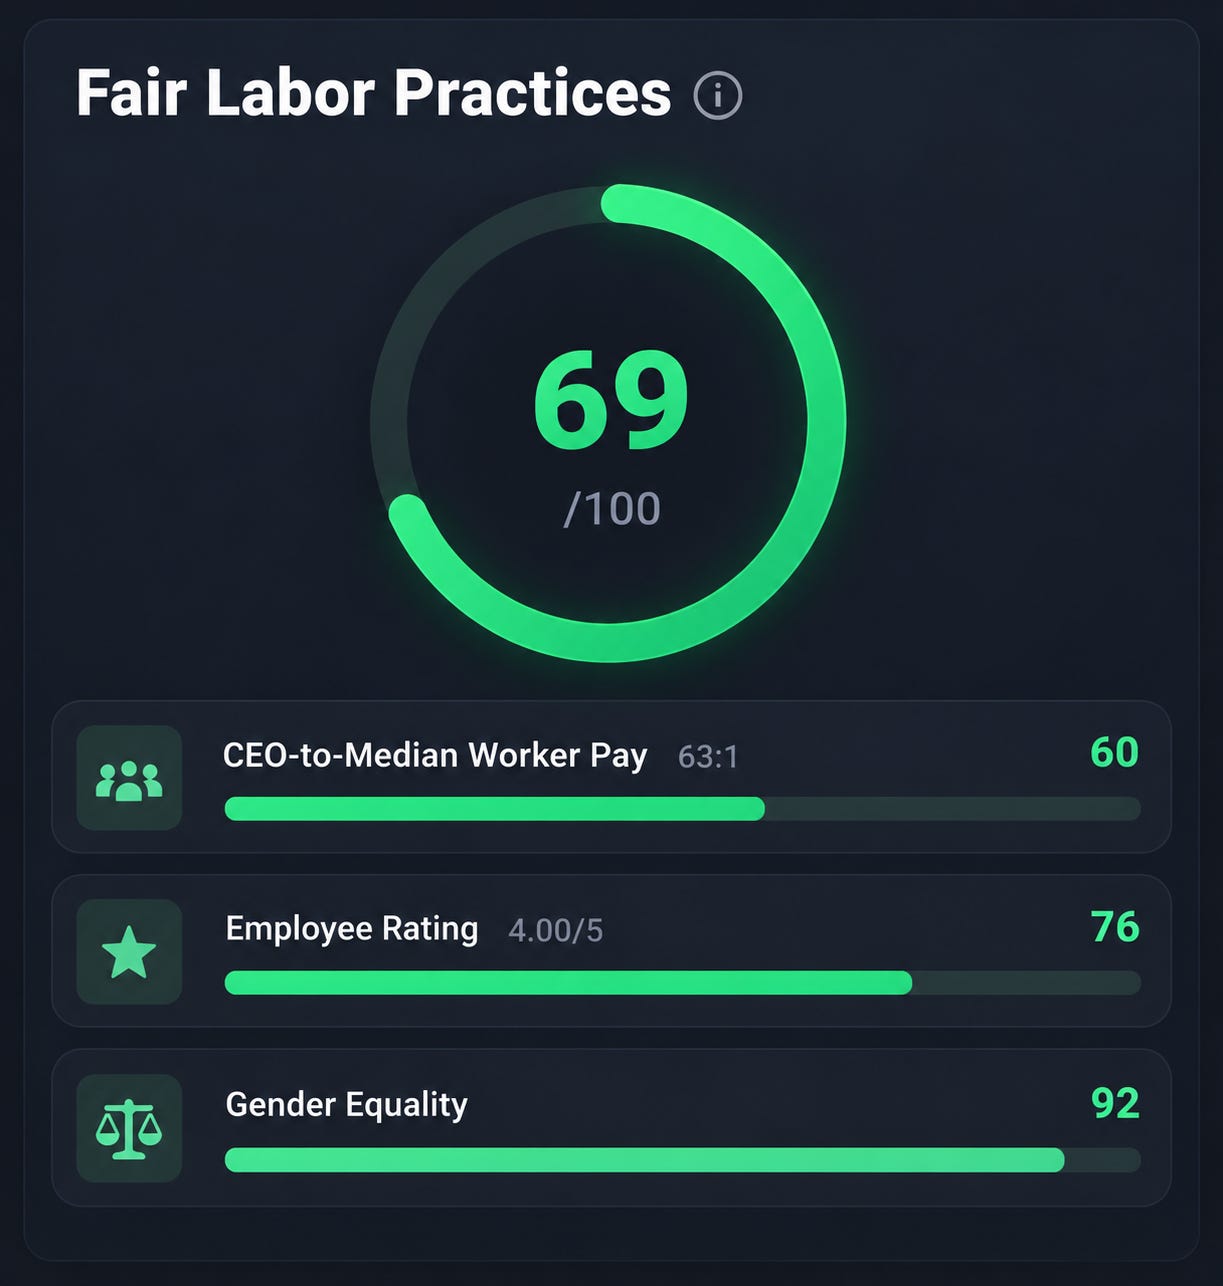
e.l.f. was the first beauty company to get a factory Fair Trade Certified. Certified factories are audited on worker rights, safety and pay, and workers spend their premium through committees they elect. The certified share was 73% in fiscal 2025, down from more than 85% a year earlier, and doesn't yet include rhode. Ziggma's Fair Labor score of 69 lines up: CEO pay is 63x the median worker's, about a fifth of the 312x average at S&P 500 companies in 2025, according to the AFL-CIO. Employees rate the company 4.0 out of 5, and Gender Equality scores 92.
e.l.f.’s board is 60% women and 40% diverse, according to the company, while women hold about 28% of US public company board seats. Its Change the Board Game coalition, now over 450 companies and nonprofits, prepares diverse candidates for board seats elsewhere. e.l.f. also donates at least 2% of the prior year’s profits to causes it supports.
Operations run on 100% renewable energy, and packaging intensity was 33% below 2019 levels in fiscal 2025. But only 61% of waste is recycled, and the emissions path points to 1.9°C of warming.
Accountability scores 37, pulled down by a Peace & Justice score of 29. We can’t tie that to a single event, but in 2019 e.l.f. paid $996,080 to settle with the US Treasury after Chinese suppliers used North Korean materials in eyelash kits. e.l.f. self-reported and tightened its audits, and Ziggma shows $0 in fines today.
e.l.f. kept growing through tariffs, a $1 billion acquisition and a stock crash. Its profit plunge was mostly the price of buying a brand that’s beating expectations. At 31x earnings the stock isn’t cheap, and accountability needs watching. For investors who want fast growth from a company that treats factory workers fairly, e.l.f. is one of the clearest picks in consumer goods. You can compare it with other top scorers in our free stock screener.
______________________________________________________________________________
Disclaimer
This information is provided solely for general information and educational use. It is not intended as, and should not be construed to be, financial, investment, tax, legal, or other professional advice. Data used in the analysis is derived from third-party sources and applicable at the time of publication of the analysis. No representation or warranty is made as to the accuracy or completeness of the information or any analysis herein.
Ziggma is not registered or licensed as a financial advisor, broker-dealer, or tax professional. Readers should perform their own independent research and seek advice from appropriately qualified professionals before making any financial, investment, or legal decisions.
You should presume that, as of the date this report is published or any related communication referencing publicly traded securities or assets, Ziggma team members may hold positions in the securities or assets discussed and could benefit financially from price movements. Positions may be changed without notice.
There is no duty to revise or update the content after publication. Neither Ziggma nor any affiliated parties accept responsibility for market changes, economic developments, or subsequent events that could affect the relevance or accuracy of the information.
Forward-Looking Statements
This report may include forward-looking statements, such as forecasts, projections, estimates, or expectations regarding financial outcomes, market dynamics, or future corporate developments. These statements are based on assumptions that may not hold true, and actual results may vary materially. The author undertakes no obligation to update or revise any forward-looking statements as circumstances change.
Third-Party Data & External Sources
Certain information is sourced from third parties. Nonetheless, the accuracy, completeness, and timeliness of such information cannot be assured. Ziggma disclaims any responsibility for errors or omissions in third-party data and does not endorse, verify, or assume accountability for the methodologies or conclusions of external sources.
AI-Generated Enhancements
AI tools can be used to enhance clarity, structure, and brevity, and to assist with research organization, ideation, and analytical review.
Redistribution
You may share this report for informational purposes. However, reproduction, distribution, republication, or modification of any portion of the content, in whole or in part, without prior written consent is prohibited.
Investment Risk Disclosure
All investing carries risk of loss. Historical performance does not guarantee future outcomes. References to specific securities, companies, or strategies are for informational purposes only and do not constitute recommendations or endorsements. Any use of, or reliance on, the information in this report is entirely at the reader’s own risk.
Neither Ziggma nor affiliated parties shall be liable for any direct or indirect losses or damages of any kind arising from the use of this report or reliance on its contents. By accessing this report, you agree to indemnify and hold harmless Ziggma and affiliated parties from any claims, liabilities, or damages resulting from your use of the material.
You alone bear responsibility for your decisions. Use this information at your own discretion and risk.